A check for your family, tax-free
If something happens to you, the people who depend on you get the money within weeks. The mortgage is paid, the kids stay put, and nobody has to sell anything.
Independent life insurance, licensed in seven states
A tax-free check for your family if something happens to you, and a cash value you can borrow against while you are here. Leo and Aaron shop several A-rated carriers and show you the real numbers, for free.
Prefer to talk? Call or text (480) 407-8710.
Most people buy life insurance for what happens after. The policies we write are built to do something for you before.
If something happens to you, the people who depend on you get the money within weeks. The mortgage is paid, the kids stay put, and nobody has to sell anything.
An indexed universal life policy builds a balance tied to a market index with a floor of zero. Borrow against it, tax-free, for retirement income or a rough year.
Most of the policies we write let you access part of your coverage early after a critical, chronic, or terminal diagnosis. Money for treatment, not only a payout after.
We are independent, so the recommendation follows your budget and your health, not one company's product shelf.
Where most clients start
Permanent coverage with a cash value account that follows a market index and never loses money in a down year. The policy most of our clients start with.
The most coverage for the least money, for a set number of years. Built for the stretch when the mortgage is big and the kids are small.
A policy written around your loan balance and the years left on it, so the house stays in the family instead of going on the market.
A smaller whole life policy sized to the funeral, the last medical bills, and the month after. No exam, rate locked for life.
What you already have, who depends on you, and what you want the money to do. No forms first and no pitch.
We are independent. We shop several A-rated carriers and show you the actual quotes, including the ones that are not the right fit and why.
Most applications are approved without an exam, many within days. You get the policy, your family gets the beneficiary letter, and we stay your agents for the life of it.
Two independent agents who work every case the same way: real quotes from several carriers and a plain explanation of what each one does.
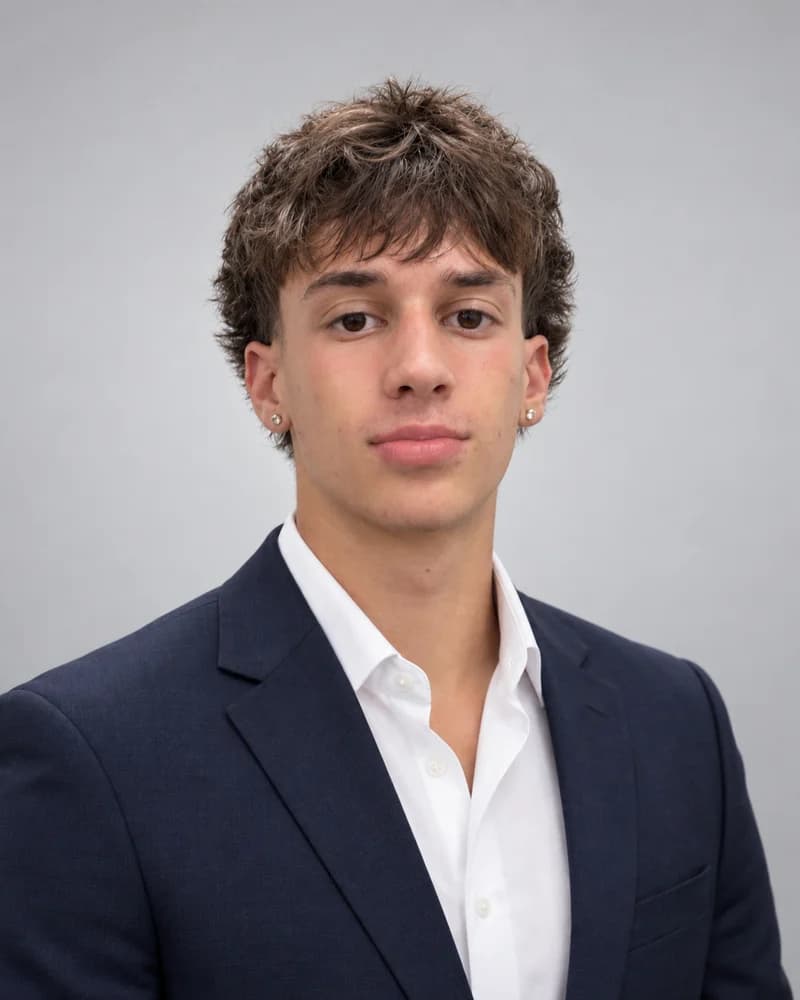
Licensed life insurance producer
Leo shops every quote across several A-rated carriers and walks you through what each policy actually does, in plain English, before you sign anything. If none of them fit, he will tell you.
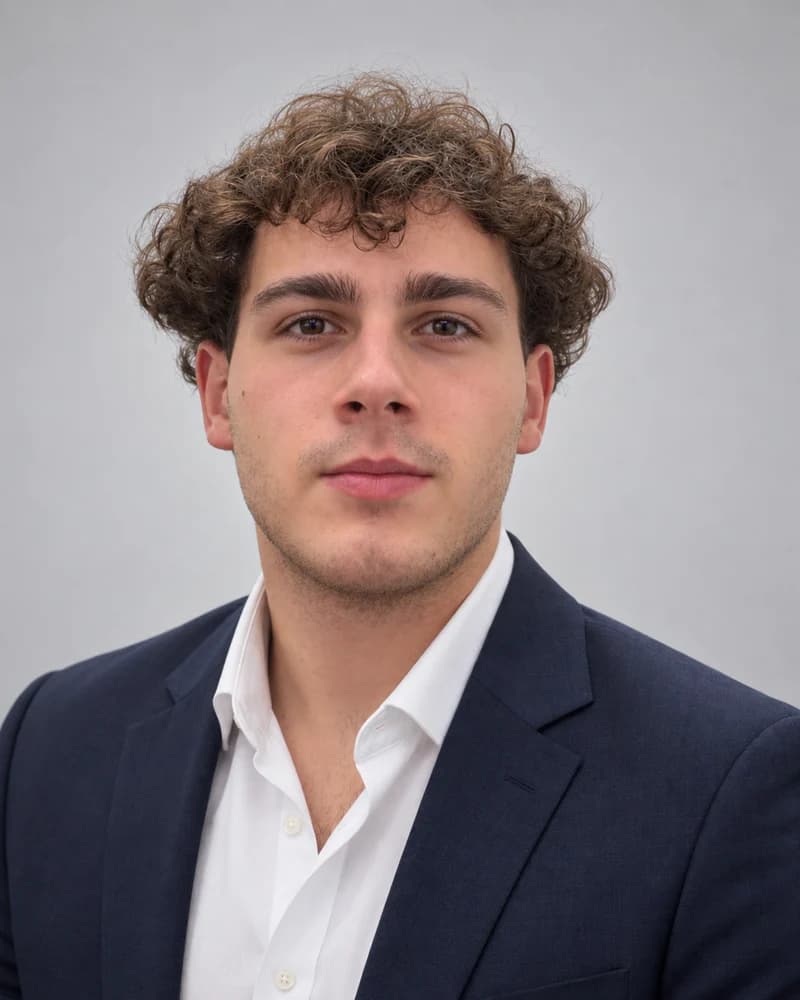
Licensed life insurance producer
Aaron starts with what you already have, who depends on you, and what you want the money to do, then builds the policy around that instead of around a product. One call, real numbers, no pressure.
We can write and service a policy in any of these states, almost always by phone and e-signature.
Every quote is compared across A-rated companies. You see the ones that fit and the ones that do not.
It is permanent life insurance with a savings account attached. Part of your premium pays for the death benefit and part goes into a cash value account that earns interest based on a market index like the S&P 500. When the index goes up, your account is credited, up to a cap. When it goes down, you are credited zero instead of losing money. You can borrow against that cash value tax-free, which is how people use it for retirement income.
No. It is life insurance. The cash value is a feature of the policy, not a brokerage account, and it is not a substitute for a 401(k) or an IRA. It is best for people who want a death benefit anyway and would rather the premium build something than disappear.
For most of what we write, no. You answer a set of health questions and many people find out within days whether they are approved. Larger coverage amounts sometimes require a quick paramedical exam at your home, and we will tell you up front if yours does.
It depends on your age, health, tobacco use, and how much coverage you want. Term life for a healthy person in their thirties is often under a dollar a day. Indexed universal life costs more because it builds cash value. Rather than guess, we run your real numbers with several carriers and show them to you side by side, for free.
Usually, yes. Diabetes, high blood pressure, and a past cancer diagnosis are all conditions carriers place regularly. Some will cover you from day one; others use a waiting period. We will tell you plainly which one you are looking at before you sign anything.
No. We are licensed in seven states and nearly everything is handled by phone, video, and e-signature, usually in one appointment.
No. LA Legacy Life is an independent agency. We are not a carrier and we are not affiliated with any government agency, Medicare, or the Social Security Administration. We are paid a commission by the insurance company if you take a policy, which is worth knowing up front.
Two short steps. We call you back within one business day with quotes from several carriers and no pressure to take any of them.
Monday to Saturday, 9am to 8pm